What Should I Compare Besides Price When I Get Multiple Offers?
The short answer
Compare how each buyer is paying (cash or a loan, and how strong the loan is), the contingencies and their deadlines, the deposit, the closing date and any rent-back, and what you'd walk away with after costs. The highest price only helps you if that buyer can close on time.
Getting more than one offer feels like the hard part is over. Then you open the offers and realize they don’t line up. One has the highest price. One is cash. One closes in three weeks, another in six. One buyer has to sell their own home first. Now you have to pick, and the price at the top of the page is only part of the story.
The goal isn’t to pick the biggest price. It’s to pick the offer most likely to close on terms that work for you.
Why The Highest Offer Isn’t Always The Strongest
An offer is a promise to buy, with conditions. The price tells you what the buyer says they’ll pay. The rest of the contract tells you how likely they are to get to closing, and how much room they have to walk away or ask for more along the way.
A buyer who offers more but can cancel over the loan, the appraisal, the inspection and the sale of their own home has given themselves a lot of ways out. A buyer who offers a little less, with fewer conditions and a short timeline, has given you more certainty. Which one is worth more to you depends on your situation.
How Is The Buyer Paying For The House?
Start with the money.
- Cash or a loan. A cash buyer has no lender who can say no. Ask for proof of funds.
- The down payment. A bigger down payment usually means a smaller loan and more room if the appraisal comes in low.
- The lender. A pre-approval letter is a start. In my experience, a call to the lender tells you more: how far along the approval is and whether they’ve closed loans like this one on time. I call the lender on every offer.
Which Contingencies Matter Most?
A contingency is a condition the buyer can use to cancel the contract. The common ones:
- Inspection. The buyer’s time to inspect the home and decide.
- Appraisal. If the home appraises below the price, the buyer may be able to cancel or ask to renegotiate.
- Loan. If the loan isn’t approved, the buyer may be able to cancel.
- Sale of the buyer’s home. The buyer needs to sell their own place first. This one can add the most uncertainty.
Look at which contingencies are in each offer and how many days each one lasts. Shorter periods mean you know sooner whether the deal is holding. I’m not an attorney, and this isn’t legal advice. If you have a question about what a contract term means for you, a real estate attorney can review it.
What Else Belongs In The Comparison?
- The deposit. How much the buyer puts down when escrow opens, and when it’s at risk for them.
- The closing date. Does it line up with your next move?
- A rent-back. If you need to stay after closing, an offer that includes it may be worth more to you than a higher price. I wrote about how a rent-back works.
- Credits and extras. Requests for closing cost credits or items that stay with the house.
What Would You Walk Away With?
Two offers with the same price can leave you with different amounts after costs, credits and timing. That’s why I put an estimated net next to each offer, so you’re comparing what lands in your account, not the headline price.
If one of your offers is from a company that buys houses for cash, I wrote about how to tell if a “We Buy Houses” offer is fair.
How I Lay Out Multiple Offers For My Sellers
This is the Offer Negotiation step of The Show-Ready-Seller® System. Here’s how it works:
- I call you when each offer comes in, and I call each buyer’s agent and lender to find out what’s behind the paper.
- You get every offer side by side the same day, with the price, the loan, the contingencies, the timing and your estimated net for each, plus my recommendation.
- We meet and decide together. You can accept one, counter one or more, or line up a backup offer. You make the call, and you’ll know why.
I’d rather you take the offer most likely to close than the one that looks best on day one and falls apart in escrow. That’s my opinion, not a guarantee. Every sale is different.
When You Have Offers To Compare
Offers come after the pricing and the launch, and the list price you start with shapes how many offers you get. To see how all five steps fit together, request the free How To Sell Your Home Guide.
Frequently Asked Questions
Should I always take the highest offer?
Not always. A higher price with a weak loan, a long list of contingencies or a buyer who has to sell their own home first can be worth less to you than a slightly lower offer that's likely to close on time. Compare what each one means for you before you decide.
Is a cash offer better than an offer with a loan?
A cash offer has no loan that can fall through, and it can often close sooner. It isn't automatically better. A loan offer with a strong lender, a solid down payment and a higher price can be the stronger choice. Ask for proof of funds from a cash buyer.
Can I counter more than one buyer at the same time?
Yes. You can send counter offers to more than one buyer, and there are contract forms built for it so you don't end up accepting two deals. Your agent should walk you through how that works before anything goes out.
What is a backup offer?
A backup offer is a second buyer who agrees to step into first place if your first deal cancels. It gives you a plan if escrow falls apart, without starting over.
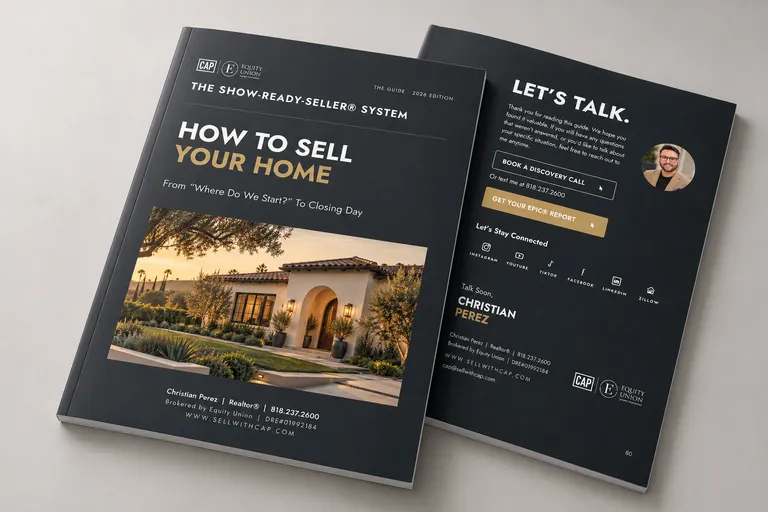
Free Guide
How To Sell Your Home Guide
This guide comes from what I've learned selling homes in Burbank and the San Fernando Valley since 2015, not from general advice written for every market in the country. It shows you the steps I'd take on your home, so you know what to do before you spend money or sign anything.
Request My Free Guide